

“Based on the latest BEI evaluation results, MTEL will become the new constituent of IDX ESG Leaders starting September 21, 2022”
JAKARTA, September 16, 2022 – The Indonesia Stock Exchange (BEI) is evaluating the IDX ESG Leaders Index, in which shares of PT Dayamitra Telekomunikasi Tbk. (MTEL) are included as new members of the IDX ESG Leaders Index which will come into force on September 21, 2022.
The IDX ESG Leaders Index is designed to measure the price performance of shares, demonstrating commendable Environmental, Social, and Governance (ESG) assessments, not involved in significant controversy, strong transaction liquidity, and commendable financial performance. The ESG assessment and controversy analysis was executed by Sustainalytics.
The inclusion of MTEL in the IDX ESG Leaders stock list further strengthens the company’s vision and mission in environmental preservation, social welfare, and good corporate governance (GCG). Mitratel’s Investment Director, Hendra Purnama affirmed that the company’s efforts so far has exemplified its vision and mission to implementing ESG principles.
“In the environmental sector, MTEL possesses over 615 off-grid towers powered by solar panels. Furthermore, MTEL has also established research and development facilities for solar panels as a source of electricity in two on-grid locations, located in Sisalam Village, Wanasari, Brebes, Central Java and in Bukit Tengah, Bali,” said Hendra in Jakarta, Friday. (9/16/2022). Hendra further explained that Mitratel also aided during the Covid-19 pandemic, including the free Breakfast and Basic Food Program and ventilator assistance to hospitals.
“We are taking this initiative as a form of the company’s commitment to consistently share with others and foster mutual growth with the community,” continued Hendra Purnama.
Concerning corporate governance, Hendra stated that the company had attained ISO 31000 Risk Management Certification, ISO 45001 Occupational Health, and Safety and SMK3 Certification. “We are currently in the evaluation process to achieve ISO 9001:2008 certification regarding quality management systems and ISO 27000 regarding information security management systems,” he added.
The IDX ESG Leaders Index was developed based on an ESG risk assessment, which measures the degree to which ESG practices are implemented by listed companies based on risk exposure in each business sector. BEI collaborates with Sustainalytics, a prominent independent institution engaged in ESG research and corporate governance, providing ESG data. The ESG data provided encompasses ESG risk assessments and controversy analysis, determining the constituents of the IDX ESG Leaders Index.
“Berdasarkan hasil evaluasi terbaru BEI, MTEL jadi penghuni baru IDX ESG leaders mulai 21 September 2022”
JAKARTA, 16 September 2022 – Bursa Efek Indonesia (BEI) melakukan evaluasi terhadap indeks IDX ESG Leaders dimana saham PT Dayamitra Telekomunikasi Tbk (MTEL) atau “Mitratel” masuk dalam daftar anggota baru indeks IDX ESG Leaders yang akan mulai berlaku pada 21 September 2022.
Indeks IDX ESG Leaders adalah indeks yang mengukur kinerja harga dari saham-saham yang memiliki penilaian Environmental, Social, dan Governance (ESG) yang baik dan tidak terlibat pada kontroversi secara signifikan, memiliki likuiditas transaksi serta kinerja keuangan yang baik. Penilaian ESG dan analisis kontroversi dilakukan oleh Sustainalytics.
Masuknya MTEL dalam daftar saham penghuni IDX ESG Leaders semakin mengokohkan visi misi perusahaan dalam pelestarian lingkungan, kepedulian sosial dan tata kelola yang baik (GCG). Direktur Investasi Mitratel Hendra Purnama mengatakan, kiprah perusahaan selama ini telah membuktikan visi dan misinya dalam menerapkan prinsip ESG.
“Di bidang lingkungan, MTEL memiliki lebih dari 615 tower off grid dengan sumber listrik menggunakan panel tenaga surya. Lebih jauh saat ini MTEL juga telah membangun lokasi riset dan pengembangan solar panel sebagai sumber listrik untuk lokasi site on grid di 2 lokasi yaitu di Desa Sisalam, Wanasari, Brebes, Jawa Tengah dan di Bukit Tengah, Bali,” ungkap Hendra di Jakarta, Jumat (16/9/2022). Hendra mengungkapkan Mitratel juga memberikan bantuan dan dukungan selama pandemi Covid-19 diantaranya Program Sarapan dan Sembako gratis dan bantuan ventilator ke rumah sakit.
“Langkah ini kami lakukan sebagai bentuk kepedulian perusahaan untuk selalu berbagi dengan sesama, dan kami bisa tumbuh bersama masyarakat,” lanjut Hendra Purnama.
Dari sisi tata kelola perusahaan, Hendra menyatakan perusahaan telah meraih Sertifikasi ISO 31000 Risk Management, Sertifikasi ISO 45001 Occupational Health and Safety dan SMK3. “Saat ini kami sedang dalam proses evaluasi untuk meraih sertifikasi ISO 9001:2008 tentang sistem manajemen mutu/kualitas dan ISO 27000 tentang sistem manajemen keamanan informasi,” dia menambahkan.
Indeks IDX ESG Leaders dibangun berdasarkan penilaian risiko ESG yang mengukur sejauh manapenerapan ESG dilakukan oleh perusahaan tercatat berdasarkan eksposur risiko di masingmasing bidang usaha. BEI bekerjasama dengan Sustainalytics, lembaga independen terkemuka yang bergerak dalam bidang penelitian ESG dan tata kelola perusahaan, dalam penyediaan data ESG. Data ESG yang disediakan berupa penilaian risiko ESG dan analisis kontroversi yang akan menjadi dasar dalam penetapan konstituen Indeks IDX ESG Leaders.
Meskipun kenaikan harga BBM diprediksi bisa mendorong kenaikan inflasi dan suku bunga acuan Bank Indonesia, namun Henry Tedja, analis pasar modal PT Mandiri Sekuritas menilai dampaknya cukup terkendali bagi bisnis perusahaan menara telekomunikasi seperti PT Dayamitra Telekomunikasi Tbk (MTEL) atau Mitratel.
Prediksi itu dikarenakan MTEL memiliki kontrak jangka panjang dengan perusahaan telekomunikasi yang mempunya neraca keuangan yang kuat, terutama setelah dilakukan konsolidasi di industri.
“Secara struktur biaya, industri menara yang bersifat capital intensive (padat modal) juga memiliki pengeluaran yang relatif tetap. Hal ini tercermin dari pendapatan sebelum bunga, pajak depresiasi dan amortisasi (EBITDA) margin perusahaan menara yang cukup tinggi di kisaran 80% termasuk Mitratel. Karena itu kami melihat dampak kenaikan harga BBM terhadap kinerja perusahaan relatif terbatas,” ujar Henry di Jakarta, Rabu (7/9/2022).
Meski begitu, Henry mengingatkan kenaikan harga BBM bisa berpengaruh terhadap valuasi atau harga saham perusahaan. Sebab valuasi perusahaan menara seperti Mitratel, cenderung berbanding terbalik dengan inflasi atau suku bunga.
Hal ini karena relatif tingginya leverage yang dimiliki oleh perusahaan menara. Meskipun demikian, posisi Mitratel cukup baik mengingat tingkat leveragenya dibawah rata-rata industri.
“Akibatnya, kenaikan inflasi atau suku bunga akan memiliki pengaruh bagi saham industri menara telekomunikasi,” tuturnya.
Henry memperkirakan dalam jangka pendek, tingginya inflasi dan kenaikan suku bunga akan memberi sentimen bagi Mitratel. Namun dia memprediksi outlook perusahaan tetap positif dalam jangka menengah, terlebih setelah perusahaan mengakuisisi 6.000 menara milik Telkomsel.
“Hal ini akan mendukung pertumbuhan pendapatan dan EBITDA perusahaan dalam jangka menengah. Kami masih merekomendasikan BUY untuk saham Mitratel dengan target harga di Rp950 per saham,” ujar dia.
Pada penutupan perdagangan Senin (5/9/2022), harga saham MTEL di level Rp800 atau melemah 0,6% dibandingkan Jumat akhir pekan lalu. Namun dalam sepekan terakhir, saham MTEL naik 1,27% dan 6 bulan terakhir meningkat 3,23%.
Menurut Henry akuisisi tower yang dilakukan Mitratel terhadap 6.000 menara milik PT Telekomunikasi Selular (Telkomsel) akan berdampak positif bagi kinerja perusahaan, mengingat menara tersebut memiliki lokasi dan nilai strategis.
Akuisisi ini juga lebih cepat dari target awal yang dicanangkan, sehingga memungkinkan perusahaan untuk melakukan cross-selling lebih cepat atas menara-menara tersebut kepada perusahaan telekomunikasi lainnya seperti Indosat Ooredoo Hutchison, XL Axiata, dan Smartfren. “Hal ini tentunya akan meningkatkan outlook pertumbuhan pendapatan dan EBITDA Mitratel dalam 2 tahun mendatang,” ungkap Henry.
Hingga akhir 2022, Henry memproyeksikan Mitratel berpeluang membukukan pertumbuhan pendapatan dan EBITDA 11-13% secara tahunan (YoY). Dia menilai akuisisi tower milik Telkomsel akan lebih berdampak positif bagi bisnis Mitratel pada 2023 dibandingkan di 2022, mengingat akuisisi ini baru terjadi pada kuartal III 2022.
Sehingga dampak penyewaan menara yang baru hanya akan berkontribusi dalam beberapa bulan di tahun ini. Selain itu, konsolidasi di industri telekomunikasi juga akan mempengaruhi permintaan menara tahun ini. Di sisi lain, pertumbuhan permintaan fiber yang cukup pesat di industri menara tentunya akan berdampak positif bagi bisnis Mitratel.
“Kami melihat adanya ruang bagi market untuk melakukan revisi target revenue dan EBITDA MTEL untuk tahun 2023 dengan adanya akuisisi 6.000 menara ini,” jelasnya.
Pada semester I 2022, Mitratel berhasil membukukan laba Rp891,54 miliar, naik 27,23% dibandingkan periode sama tahun lalu Rp700,74 miliar. Laba itu sejalan dengan pendapatan yang naik 15,48% jadi Rp3,72 triliun pada semester I 2022. Laba bersih MTEL tumbuh kuat terutama berasal dari pendapatan operasional yang lebih tinggi seiring dengan pertumbuhan jumlah penyewa dan lokasi menara.
Untuk diketahui, awal Agustus 2022, Mitratel mengumumkan telah menandatangani Perjanjian Jual Beli (Sales & Purchase Agreement/SPA) untuk pengambilalihan 6.000 menara Telkomsel. Jumlah menara yang ditransaksikan ini jauh melebihi rencana aksi anorganik Mitratel yang tertuang di prospektus.
Sebanyak 6.000 menara yang diakuisisi Mitratel dari Telkomsel berada di lokasi – lokasi strategis yang tersebar di seluruh Indonesia, untuk mendukung percepatan penambahan potensi kolokasi dan pengembangan tower related business.
Mitratel juga telah menyiapkan infrastruktur telekomunikasi, baik itu menara, fiber optic dan power to tower yang tersebar di seluruh Indonesia, khususnya di luar Jawa, yang akan memberikan kemudahan kepada operator-operator telekomunikasi, maupun non operator untuk memanfaatkan solusi terlengkap dan terintegrasi yang telah dimiliki oleh Mitratel.
(fik)
Sumber:
Okezone

Bisnis.com, JAKARTA – PT Dayamitra Telekomunikasi Tbk. (MTEL) or Mitratel last month acquired 6,000 towers belonging to PT Telekomunikasi Selular (Telkomsel). Analysts assess that this acquisition will have a positive impact on MTEL’s performance. Mandiri Sekuritas Capital Market Analyst Henry Tedja said that this acquisition would have a positive impact on the company’s performance, considering that the tower has a strategic location and value. Apart from that, continued Henry, this acquisition was also faster than the initial target planned, thereby enabling the company to carry out faster cross-selling of these towers to other telecommunications companies such as Indosat Ooredoo Hutchison, XL Axiata, and Smartfren.
“This will certainly improve Mitratel’s revenue and EBITDA growth outlook in the next 2 years,” said Henry, Wednesday (7/9/2022).
Until the end of 2022, Henry projects that Mitratel will have the opportunity to record revenue and EBITDA growth of 11-13 percent annually (YoY). He believes that the acquisition of Telkomsel’s tower will have a more positive impact on Mitratel’s business in 2023 than in 2022, considering that this acquisition only occurred in the 111/2022 quarter.
Henry sees the impact that the new tower rental will only have in a few months this year. Apart from that, consolidation in the telecommunications industry will also affect tower demand this year. On the other hand, the rapid growth in demand for fiber in the tower industry will certainly have a positive impact on Mitratel’s business.
“We see that there is room for the market to revise MTEL’s revenue and EBITDA targets for 2023 with the acquisition of these 6,000 towers,” he said. Henry said that his party still recommends buying Mitratel shares, with a target price of IDR 950 per share.
For your information, in early August 2022, Mitratel announced that it had signed a Sales & Purchase Agreement (SPA) for the takeover of 6,000 Telkomsel towers. The number of towers transacted far exceeds Mitratel’s inorganic action plan stated in the prospectus.
A total of 6,000 towers acquired by Mitratel from Telkomsel are in strategic locations spread throughout Indonesia, to support the acceleration of additional collocation potential and development of tower related business.
Mitratel has also prepared telecommunications infrastructure, including towers, fiber optic and power to tower spread throughout Indonesia, especially outside Java. It is believed that this will make it easier for telecommunications operators and non-operators to utilize the most complete and integrated solutions that Mitratel has.
Even though the increase in fuel prices is predicted to push up inflation and Bank Indonesia’s benchmark interest rate, Henry Tedja, capital market analyst at PT Mandiri Sekuritas, assesses that the impact is quite manageable for the business of telecommunications tower companies such as PT Dayamitra Telekomunikasi Tbk (MTEL) or Mitratel. This prediction is because MTEL has long-term contracts with telecommunications companies that have strong financial balance sheets, especially after consolidation in the industry.
“In terms of cost structure, the tower industry which is capital intensive also has relatively fixed expenses. This is reflected in the earnings before interest, tax, depreciation and amortization (EBITDA) margin of tower companies which is quite high in the range of 8096 including Mitratel. “Because of that, we see that the impact of rising fuel prices on company performance is relatively limited,” said Henry in Jakarta, Wednesday (7/9/2022).
Even so, Henry reminded that the increase in fuel prices could affect the company’s valuation or share price. Because the valuation of tower companies such as Mitratel tends to be inversely proportional to inflation or interest rates.
This is due to the relatively high leverage owned by tower companies. Nevertheless, Mitratel’s position is quite good considering its leverage level is below the industry average.
“As a result, an increase in inflation or interest rates will have an impact on shares in the telecommunications tower industry,” he said.
Henry estimates that in the short term, high inflation and rising interest rates will provide sentiment for Mitratel. However, he predicts that the company’s outlook will remain positive in the medium term, especially after the company acquired Telkomsel’s 6,000 towers.
“This will support the company’s revenue and EBITDA growth in the medium term. “We still recommend BUY for Mitratel shares with a target price of IDR 950 per share,” he said.
At the close of trading Monday (5/9/2022), MTEL’s share price was at IDR 800 or down 0.6% compared to Friday last week. However, in the last week, MTEL shares rose 1.27% and in the last 6 months they increased 3.23%.
According to Henry, Mitratel’s tower acquisition of 6,000 towers belonging to PT Telekomunikasi Selular (Telkomsel) will have a positive impact on the company’s performance, considering that these towers have a strategic location and value.
This acquisition is also faster than the initial target set, thus enabling the company to cross-sell these towers more quickly to other telecommunications companies such as Indosat Ooredoo Hutchison, XL Axiata, and Smartfren. “This will certainly improve Mitratel’s revenue and EBITDA growth outlook in the next 2 years,” said Henry.
Until the end of 2022, Henry projects that Mitratel will have the opportunity to record revenue and EBITDA growth of 11-13% annually (YoY). He believes that the acquisition of Telkomsel’s tower will have a more positive impact on Mitratel’s business in 2023 than in 2022, considering that this acquisition only occurred in the third quarter of 2022.
So the impact of leasing the new tower will only contribute for a few months this year. Apart from that, consolidation in the telecommunications industry will also affect tower demand this year. On the other hand, the fairly rapid growth in demand for fiber in the tower industry will certainly have a positive impact on Mitratel’s business.
“We see that there is room for the market to revise MTEL’s revenue and EBITDA targets for 2023 with the acquisition of these 6,000 towers,” he explained.
In the semester | In 2022, Mitratel managed to record a profit of IDR 891.54 billion, an increase of 27.23% compared to the same period last year of IDR 700.74 billion. This profit is in line with revenue which rose 15.48% to IDR 3.72 trillion. MTEL’s net profit grew strongly mainly from higher operating income in line with growth in the number of tenants and tower locations.
For your information, in early August 2022, Mitratel announced that it had signed a Sales & Purchase Agreement (SPA) for the takeover of 6,000 Telkomsel towers. The number of towers transacted far exceeds Mitratel’s inorganic action plan stated in the prospectus.
A total of 6,000 towers acquired by Mitratel from Telkomsel are in strategic locations spread throughout Indonesia, to support the acceleration of additional collocation potential and development of tower related business.
Mitratel has also prepared telecommunications infrastructure, including towers, fiber optic and power to tower spread throughout Indonesia, especially outside Java, which will make it easier for telecommunications operators and non-operators to utilize the most complete and integrated solutions they have by Mitratel.
PT Dayamitra Telekomunikasi Tbk. (MTEL) atau Mitratel bulan lalu melakukan akuisisi 6.000 menara milik PT Telekomunikasi Selular (Telkomsel).
Bisnis.com, JAKARTA – PT Dayamitra Telekomunikasi Tbk. (MTEL) atau Mitratel bulan lalu melakukan akuisisi 6.000 menara milik PT Telekomunikasi Selular (Telkomsel). Analis menilai akuisisi ini akan berdampak positif terhadap kinerja MTEL. Analis Pasar Modal Mandiri Sekuritas Henry Tedja mengatakan, akuisisi ini akan berdampak positif bagi kinerja perusahaan, mengingat menara tersebut memiliki lokasi dan nilai strategis. Selain itu, lanjut Henry, akuisisi ini juga lebih cepat dari target awal yang dicanangkan, sehingga memungkinkan perusahaan untuk melakukan cross-selling lebih cepat atas menara-menara tersebut kepada perusahaan telekomunikasi lainnya seperti Indosat Ooredoo Hutchison, XL Axiata, dan Smartfren.
“Hal ini tentunya akan meningkatkan outlook pertumbuhan pendapatan dan EBITDA Mitratel dalam 2 tahun mendatang,” kata Henry, Rabu (7/9/2022).
Hingga akhir 2022, Henry memproyeksikan Mitratel berpeluang membukukan pertumbuhan pendapatan dan EBITDA 11-13 persen secara tahunan (YoY). Dia menilai akuisisi tower milik Telkomsel akan lebih berdampak positif bagi bisnis Mitratel pada 2023 dibandingkan di 2022, mengingat akuisisi ini baru terjadi pada kuartal III/2022.
Henry melihat dampak penyewaan menara yang baru hanya akan berkontribusi dalam beberapa bulan di tahun ini. Selain itu, konsolidasi di industri telekomunikasi juga akan mempengaruhi permintaan menara tahun ini. Di sisi lain, pertumbuhan permintaan fiber yang cukup pesat di industri menara tentunya akan berdampak positif bagi bisnis Mitratel.
“Kami melihat adanya ruang bagi market untuk melakukan revisi target revenue dan EBITDA MTEL untuk tahun 2023 dengan adanya akuisisi 6.000 menara ini,” ucapnya.
Henry menuturkan, pihaknya masih merekomendasikan beli untuk saham Mitratel, dengan target harga di Rp950 per saham.
Untuk diketahui, awal Agustus 2022, Mitratel mengumumkan telah menandatangani Perjanjian Jual Beli (Sales & Purchase Agreement/SPA) untuk pengambilalihan 6.000 menara Telkomsel. Jumlah menara yang ditransaksikan ini jauh melebihi rencana aksi anorganik Mitratel yang tertuang di prospektus.
Sebanyak 6.000 menara yang diakuisisi Mitratel dari Telkomsel berada di lokasi–lokasi strategis yang tersebar di seluruh Indonesia, untuk mendukung percepatan penambahan potensi kolokasi dan pengembangan tower related business.
Mitratel juga telah menyiapkan infrastruktur telekomunikasi, baik itu menara, fiber optic dan power to tower yang tersebar di seluruh Indonesia, khususnya di luar Jawa. Hal ini diyakini akan memberikan kemudahan kepada operator-operator telekomunikasi, maupun non-operator untuk memanfaatkan solusi terlengkap dan terintegrasi yang telah dimiliki oleh Mitratel.
Sumber:
Bisnis.com

Jakarta, March 15, 2022 – Shares of PT Dayamitra Telekomunikasi (Mitratel) Tbk. demonstrates potential for acquisition. This is owing to MTEL’s strong fundamentals. MTEL’s performance throughout 2021 exceeded analysts’ expectations.
In this regard, PT Samuel Sekuritas Indonesia Senior Capital Market Analyst, Yosua Zisokhi, recommends “purchase” MTEL shares. “MTEL shares are worth acquiring (“purchasing”) at the current price,” he said. Joshua said that MTEL valuation is fundamentally considered favorable. “From what I see, MTEL shares are considerably favorable, offering room for MTEL shares to move up. That’s because MTEL shares are considerably cheap at the current price,” emphasized Yosua. Last year, MTEL obtained Initial Public Offering (IPO) funds amounting to IDR 18.8 trillion, enabling new tower acquisitions and revenue growth. “In my opinion, this aspect makes MTEL shares worth investing at their current valuation,” he said. MTEL logged impressive revenue growth in 2021 of 11% to IDR 6.87 trillion, compared to 2020 of IDR 6.18 trillion. MTEL also succeeded in increasing EBITDA to reach IDR 5.18 trillion in 2021, marking a notable increase of 23.9% compared to 2020 of IDR 4.18 trillion. Apart from that, MTEL has implemented a lot of efficiency measures, especially concerning depreciation. This made MTEL’s net profit rise significantly by nearly 13,096 amounting to IDR 1.38 trillion, a significant rise from IDR 602 billion in 2020 of. Then, MTEL’s net profit margin surged to 20.1% last year, from 9.7% in 2020. “MTEL’s performance achievements last year exceeded our expectations since we estimated it would be slightly below that. Overall, it is exceptionally wonderful for MTEL to start in 2022,” he said. In 2022, MTEL will reportedly acquire another tower. “That’s what we’ve been waiting for. Moreover, now MTEL has substantial funds after the IPO of tens of trillions, which will be allocated for acquisitions. I think this shows MTEL’s commendable performance,” concluded Yosua. Last year, MTEL acquired 8,139 Telkomsel towers and 798 Telkom towers, leveraging its revenue flow. MTEL’s exceptional revenue flow is obtained from tower rental contracts spanning approximately 10 years, contributing to MTEL’s promising future. “Consequently, in the next 10 years, MTEL will achieve consistent income compared to that of 2021. Therefore, to foster revenue and net profit, MTEL only needs to add around 500 – 750 new towers per year. I think it is an exceptional number,” he said. Yosua emphasized that the consolidation carried out by the Telkom Group has substantially strengthened MTEL. Compared to others, MTEL stands out as one of the largest companies, demonstrating MTEL’s strong purchasing and bargaining power, especially as it is supported by the TelkomGroup, where Telkomsel serves as the linchpin of MTEL’s revenue. “If we are looking ahead with massive 5G services, the demand for towers is likely surging up,” concluded Yosua.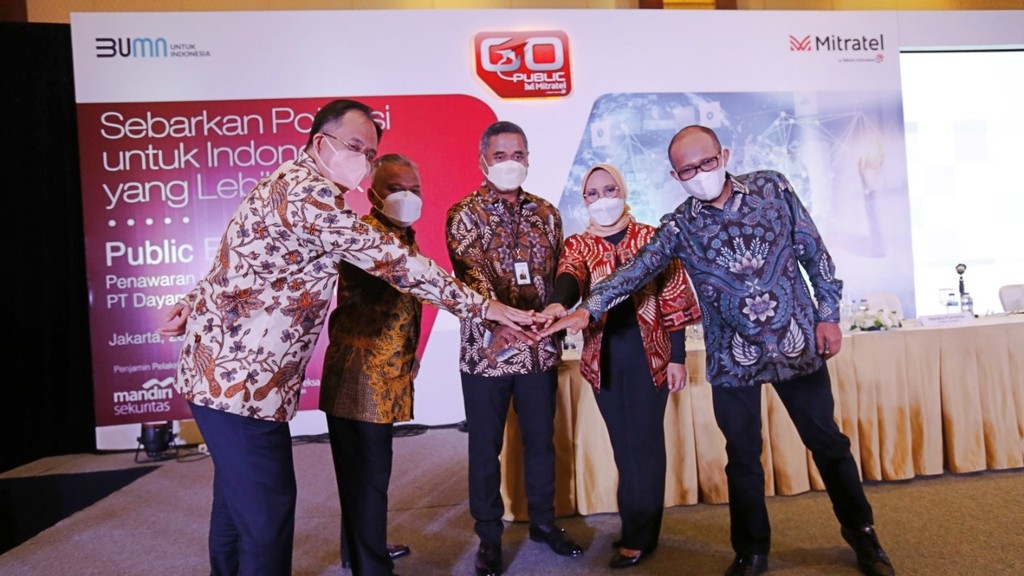
Aksi akuisisi PT Dayamitra Telekomunikasi Tbk (MTEL) atau Mitratel terhadap 6.000 menara milik PT Telekomunikasi Selular (Telkomsel) diprediksi akan berdampak positif bagi kinerja MTEL. Sebab transaksi ini berpeluang mendorong pertumbuhan organik kinerja Mitratel tahun ini dan tahun depan.
Equity Research Analyst PT BCA Sekuritas Mohammad Fakhrul Arifin mengatakan akuisisi Mitratel terhadap menara Telkomsel dengan nilai transaksi mencapai Rp 10,28 triliun. Dalam transaksi ini juga disepakati perjanjian sewa kembali 6.000 menara oleh Mitratel kepada Telkomsel, komitmen Telkomsel untuk memesan 1.000 BTS dari Mitratel dalam 3 tahun ke depan, serta sewa 712 lahan milik Telkomsel tempat menara tersebut berada.
“Kami melihat akuisisi ini akan menjadi hal positif bagi prospek kinerja Mitratel. Akuisisi ini membutuhkan sekitar 73,4 persen dari proyeksi kami atas belanja modal Mitratel di 2022. Perlu dicatat bahwa rasio sewa menara yang diakuisisi mencapai 1 kali karena sebelumnya menara ini eksklusif hanya untuk Telkomsel,” ujar Fakhrul dalam keterangan, Rabu (31/8).
Fakhrul menilai Mitratel memiliki struktur permodalan yang kuat dengan alokasi belanja modal cukup besar yakni Rp 14 triliun. Kuatnya permodalan ini bisa mendorong Mitratel memperbesar skala perusahaan dan memperkuat ekspansi organik dan anorganik.
Menurutnya, Dengan memiliki total lebih dari 34.800 menara dan 49.900 penyewa, menyiratkan ada 1,43x rasio kolokasi. Penurunan ini pada dasarnya logis dalam pandangan kami, mengingat menara yang diperoleh dari akuisisi sebelumnya hanya dipakai oleh Telkomsel.
“Sebab transaksi ini pada akhirnya akan mendorong pertumbuhan nilai perusahaan, sehingga memberikan potensi tambahan pertumbuhan sekitar 2-3 persen, sesuai dari prediksi terbaru perusahaan dan sejalan dengan perkiraan kami,” katanya.
Dari sisi operasional, menurut Fakhrul, dampak transaksi akuisisi menara Telkomsel ini akan bisa dilihat dalam kinerja Mitratel pada kuartal IV 2022 dan proyeksi kinerja 2023. Meskipun nantinya bisa berdampak rasio kinerja nonorganik, namun dia memprediksi penggerak utama pertumbuhan Mitratel di semester II 2022 ialah dari segmen organik yang berpotensi tumbuh lebih sehat dan mendongkrak rasio kolokasi.
“Oleh karena itu, kami mengubah prospek proyeksi kami atas rasio kolokasi Mitratel menjadi 1,46x dan 1,5x pada 2022 dan 2023,” dia menjelaskan.
BCA Sekuritas memberikan rekomendasi beli (buy) terhadap saham MTEL dengan target Rp 950 per saham. Target harga saham itu mempertimbangkan rata-rata pertumbuhan tahunan (CAGR) pendapatan Mitratel pada 2021-2023 diprediksi 12,2 persen dan pendapatan perusahaan yang belum dikurangi bunga, pajak, depresiasi, dan amortisasi (EBITDA) 14,2 persen di periode yang sama. Hal itu menyiratkan EV/EBITDA 13,4x.
Harga saham MTEL pada penutupan perdagangan Jumat (26/8/2022) di level Rp 795 per saham. Sepekan dan 6 bulan terakhir, harga saham MTEL meroket 15 persen, serta setahun terakhir, melesat 30 persen.
Kinerja Semester I 2022
Dalam risetnya, Fakhrul mengungkapkan MTEL membukukan laba bersih di semester I 2022 senilai Rp 892 miliar, atau tumbuh 27 persen secara tahunan. Laba bersih MTEL yang tumbuh kuat terutama berasal dari pendapatan operasional yang lebih tinggi seiring dengan pertumbuhan jumlah penyewa dan lokasi menara.
“Perusahaan telah berhasil mempertahankan posisi leverage-nya di tingkat yang sehat, jauh di bawah perjanjian utangnya. Meskipun rencana akuisisi MTEL mungkin butuh modal besar, namun kami melihat perusahaan tidak akan butuh banyak utang. Sebab perusahaan masih mengantongi cukup dana dari IPO,” dia menjelaskan.
Fakhrul percaya kebutuhan serat optik sangat penting di tengah digitalisasi. Mitratel yang telah merealisasi 89 persen dari target serat optik di 2022, perseoran berpeluang meraih keuntungan di era jaringan 5G. “Ke depan, momentum pertumbuhan yang lebih sehat pasca konsolidasi, seharusnya terjamin,” kata dia.
Sumber:
Kumparan BISNIS
PT Dayamitra Telekomunikasi Tbk (MTEL) or Mitratel’s acquisition of 6,000 towers belonging to PT Telekomunikasi Selular (Telkomsel) is predicted to have a positive impact on MTEL’s performance. Because this transaction could encourage organic growth in Mitratel’s performance this year and next year.
Equity Research Analyst PT BCA Sekuritas Mohammad Fakhrul Arifin said Mitratel’s acquisition of the Telkomsel tower with a transaction value reached IDR 10.28 trillion. In this transaction, an agreement was also agreed to lease back 6,000 towers from Mitratel to Telkomsel, Telkomsel’s commitment to order 1,000 BTS from Mitratel in the next 3 years, as well as the lease of 712 land owned by Telkomsel where the towers are located.
“We see that this acquisition will be a positive thing for Mitratel’s performance prospects. “This acquisition requires around 73.4 percent of our projection for Mitratel’s capital expenditure in 2022. It should be noted that the rental ratio for the acquired tower reached 1 times because previously this tower was exclusive only to Telkomsel,” said Fakhrul in a statement, Wednesday (31/8) .
Fakhrul assesses that Mitratel has a strong capital structure with a large capital expenditure allocation of IDR 14 trillion. This strong capital can encourage Mitratel to expand the company’s scale and foster organic and inorganic expansion. According to him, having a total of more than 34,800 towers and 49,900 tenants implies a 1.43x collocation ratio. This reduction is basically logical in our view, considering that the towers obtained from the previous acquisition were only used by Telkomsel.
“Because this transaction will ultimately encourage growth in the company’s value, thereby providing additional growth potential of around 2-3 percent, according to the company’s latest predictions and in line with our estimates,” he said.
From the operational side, according to Fakhrul, the impact of the Telkomsel tower acquisition transaction will be seen in Mitratel’s performance in the fourth quarter of 2022 and projected performance for 2023. Although it could later impact non-organic performance ratios, he predicts that the main driver of Mitratel’s growth in the first semester of 2022 will be from organic segment that has the potential to grow healthier and increase the collocation ratio.
“Therefore, we are changing our projected outlook for Mitratel’s colocation ratio to 1.46x and 1.5x in 2022 and 2023,” he explained.
BCA Sekuritas provides a buy recommendation for MTEL shares with a target of IDR 950 per share. The share price target takes into consideration the average annual growth (CAGR) of Mitratel’s revenue in 2021-2023 which is predicted to be 12.2 percent and the company’s income before deducting interest, taxes, depreciation and amortization.
(EBITDA) 14.2 percent in the same period. That implies an EV/EBITDA of 13.4x. MTEL’s share price at the close of trading Friday (26/8/2022) was at IDR 795 per share. In the last week and 6 months, MTEL’s share price has skyrocketed 15 percent, and in the last year, it has shot up 30 percent.
Semester-I 2022 Performance
In his research, Fakhrul revealed that MTEL posted a net profit in the first semester of 2022 worth IDR 892 billion or growing 27 percent annually. MTEL’s strong net profit growth mainly came from higher operating income in line with growth in the number of tenants and tower locations.
“The company has managed to maintain its leverage position at a healthy level, well below its debt covenants. Even though MTEL’s acquisition plan may require large capital, we see that the company will not need a lot of debt. “Because the company still has enough funds from the IPO,” he explained.Fakhrul believes the need for fiber optics is very important amid digitalization. Mitratel has realized 89 percent of its fiber optic target in 2022, the company could gain profits in the 5G network era. “In the future, healthier growth momentum after consolidation should be guaranteed,” he said.

NUSA DUA, investor.id – PT Dayamitra Telekomunikasi Tbk (MTEL) atau Mitratel optimistis konsolidasi menara Telkom Group dan operator yang terjadi di industri seluler saat ini akan membawa dampak positif bagi perusahaan penyedia menara.
Bagi Mitratel sebagai market leader kepemilikan menara telekomunikasi yang terbesar di Asia Tenggara, langkah konsolidasi tersebut akan membantu dan membuka kesempatan bagi semua operator dalam melakukan ekspansi bisnisnya.
“Tumbuhnya kebutuhan mobile data, berkembangnya teknologi 5G dan IoT (Internet of Things) serta aksi merger operator seluler membawa dampak semakin berkembangnya industri menara telekomunikasi di Indonesia. Hal ini merupakan potensi pasar yang cukup bagus untuk terus bertumbuh,” kata Direktur Utama Mitratel Theodorus Ardi Hartoko dalam acara Telkom Group Investor Day 2022 di Nusa Dua, Bali, baru-baru ini.
Mitratel kini memiliki 34.800 menara, setelah mengakuisisi 6.000 menara Telkomsel yang lokasinya strategis, tersebar di seluruh Indonesia, dan mayoritas berada di luar Jawa. Mitratel juga menyediakan solusi total melalui skema bundling, yang terdiri atas tower leasing, connectivity, dan power to tower, sehingga menjadikan Mitratel memiliki kekuatan penuh dalam menjawab peluang tersebut.
“Dengan mapping tersebut, kami optimistis strategi ini akan disambut positif oleh semua operator. Apalagi, ditambah 32% menara Mitratel merupakan prioritas utama tenant dari operator seluler,” kata Teddy Hartoko, panggilan akrabnya.
Dia menegaskan, setelah akuisisi menara Telkomsel, pihaknya lebih agresif meningkatkan tenancy ratio dan perluasan layanan termasuk bisnis pendukung agar dapat meningkatkan nilai lebih bagi bisnis pelanggan. “Skema bisnis dan total solusi yang kami tawarkan kepada para operator tidak memerlukan investasi yang besar, sehingga customer menjadi dimudahkan dan efisien,” jelasnya.
Sementara itu, Direktur Utama PT Telkom Indonesia Tbk (TLKM) Ririek Adriansyah mengatakan, konsolidasi bisnis konektivitas akan memperbesar valuasi anak-anak usaha Telkom. Hal itu sudah dilakukan dengan bisnis menara telekomunikasi yakni menggabungkan menara Telkomsel ke dalam Mitratel. “Dengan penggabungan ini, unlocking bisnis sektor telekomunikasi di bawah Telkom Group dapat terlaksana,” ujarnya.
Ririek menambahkan langkah mengkonsolidasikan bisnis anak usaha TLKM merupakan realisasi dari 5 strategi besar yang dikenal dengan Five Bold Moves, untuk menjadi industri telekomunikasi kelas dunia dengan target antara lain mendorong transformasi bisnis, meningkatkan kapitalisasi pasar (market cap) dengan valuasi Rp 500-700 triliun, unlocking bisnis, serta EBITDA yang harus terus bertumbuh.
Pada kesempatan tersebut, Wakil Menteri BUMN II Kartika Wirjoatmodjo mengatakan langkah penggabungan bisnis menara di anak usaha Telkom dinilai tepat. Ia menjelaskan strategi bisnis akusisi menara Telkomsel oleh Mitratel tersebut justru membuat efisien dan meningkatkan valuasi, serta daya saing perusahaan.
Hal ini terlihat ke depan pengelolaan menara telekomunikasi milik Mitratel bisa disewakan ke semua operator seluler. Selain itu, langkah bisnis akuisisi menara yang dilakukan oleh Mitratel menjadi revenue stream baru bagi Telkom Group serta ditambah masuknya permodalan (Mitratel) dari investor. “Pengelolaan menara yang tadinya cost center, saat ini bisa jadi profit centerkarena juga bisa diisi oleh operator lain,” paparnya.
Tiko juga menyatakan UU Cipta Kerja memungkinkan dan mendorong penggunaan infrastruktur menara untuk layanan bersama (infrastructure sharing). Selain menara, fiber optik juga bisa digunakan bersama oleh operator. Menurutnya, level persaingannya saat ini bukan lagi di penguasaan infrastruktur, tapi kualitas layanan kepada pelanggan.
Editor : Jauhari Mahardhika (jauhari@investor.co.id)
Sumber:
Investor.ID
Telkom Landmark Tower, Lantai 25-27
Jl. Gatot Subroto Kav. 52 Jakarta, 12710, Indonesia
mitratel@mitratel.co.id
fax: 021 2277 0817
PT Dayamitra Telekomunikasi Tbk. or Mitratel is a subsidiary of PT Telkom Indonesia (Persero) Tbk which is engaged in telecommunications infrastructure.
© 2021 — PT Dayamitra Telekomunikasi Tbk.